In March 2024, the U.S. Securities and Exchange Commission (SEC) adopted the first federal climate disclosure rule in the U.S., but it never took effect. The SEC paused it within a month of its release, stopped defending it in court in 2025, and in May 2026 voted to propose rescinding it entirely.
If you spent 2024 preparing for SEC climate reporting, that work is not wasted. The emissions inventory, governance structure, and climate risk analysis the SEC rule would have required are now being required by states, and in several cases the state versions reach further. California's first mandatory emissions reports are due November 10, 2026, and they apply to private companies as well as public ones.
This post covers where the SEC rule stands, what public companies still have to disclose without it, and what the state laws now require.
What was the SEC climate rule?
The rule, formally titled The Enhancement and Standardization of Climate-Related Disclosures for Investors, was adopted by a 3-2 vote on March 6, 2024. It would have required SEC registrants to disclose, where material:
- Climate-related risks likely to affect strategy, operations, or financial condition, plus the governance and processes used to manage them
- Climate targets, transition plans, and the use of scenario analysis or internal carbon prices
- Scope 1 and Scope 2 greenhouse gas emissions for Large Accelerated Filers and Accelerated Filers, with phased-in third-party assurance
- Financial statement effects of severe weather events above a 1% threshold
Scope 3 emissions, which appeared in the 2022 proposal, were dropped from the final rule.
Where the SEC climate rule stands now
The SEC gave two independent reasons for rescission, as set out in its rescission fact sheet: the rule exceeded its statutory authority, and it conflicted with the agency's registrant-specific, materiality-based approach to disclosure.
For practical purposes, the federal mandate is over. None of its requirements ever applied, and no company will be asked to comply unless the SEC reintroduces it in the future.
What public companies still have to disclose
Rescinding the climate rule removes the prescriptive line items. It does not remove the obligation to disclose material climate matters.
Existing SEC rules, as explained in the Commission's 2010 interpretive guidance on climate change, still require disclosure of material climate-related information in risk factors, management’s discussion and analysis, business descriptions, and legal proceedings. The SEC's own rescission proposal relies on this point: its argument is that existing rules already capture material climate risk. A current materiality assessment shows which climate risks meet that bar.
That makes accuracy just as important as if there were a climate rule. Any climate claim a public company makes, in a 10-K, a sustainability report, or an investor presentation, is still subject to anti-fraud liability. Without a standardized federal format, the company bears the full burden of getting the methodology right.
The state climate laws that are still coming
With the federal rule gone, California is now the primary mandatory climate disclosure regime in the U.S., and other states are using its laws as a template.
California SB 253: emissions reporting, due November 10, 2026
The Climate Corporate Data Accountability Act applies to U.S. entities with more than $1 billion in total annual revenue that do business in California, public or private.
- 2026: First Scope 1 and Scope 2 reports due November 10, 2026. CARB's implementing regulations received final approval from the Office of Administrative Law on October 12, 2026, which locked in that date. CARB's 2026 reporting guidance explains how to file, and we track each change in our CARB updates article.
- 2027: Scope 3 reporting begins, and limited assurance is required on Scope 1 and 2.
- 2030 onward: Assurance on Scope 1 and 2 moves toward reasonable assurance.
CARB said in its December 2024 enforcement notice that it will not penalize first-year reporters who make a good-faith effort. That leniency does not extend to 2027, when Scope 3 and assurance arrive at the same time. For a walkthrough of the reporting template, see how to report Scope 1 and 2 emissions under SB 253.
SB 253 is also being challenged in court, but the Ninth Circuit declined to pause it. It is enforceable law today.
California SB 261: climate risk reporting, currently paused
The Climate-Related Financial Risk Act applies to U.S. entities with more than $500 million in total annual revenue doing business in California. It requires a public climate-related financial risk report every two years, aligned with the Task Force on Climate-related Financial Disclosures (TCFD) framework or an equivalent such as International Sustainability Standards Board (ISSB) standards. We reviewed 100 TCFD reports filed for SB 261 to see what early filers disclosed.
The first reports were due January 1, 2026, but on November 18, 2025, the Ninth Circuit enjoined enforcement of SB 261 while it hears the U.S. Chamber of Commerce's challenge. The court heard oral argument on January 9, 2026, and has not yet ruled. CARB has opened a public docket for companies that choose to submit reports voluntarily, so far more than 100 have reported.
If the court lifts the injunction, CARB will set a new deadline. Companies in scope should have a report close to ready rather than starting from zero when that happens.
How California compares to the SEC rule
As you can see, the California Rules go much further than the SEC’s. The SEC rule applies only to public companies, only to material emissions, and never to Scope 3. SB 253 covers private companies, requires emissions reporting whether or not it is material, and adds Scope 3 in its second year.
Other states with climate disclosure bills
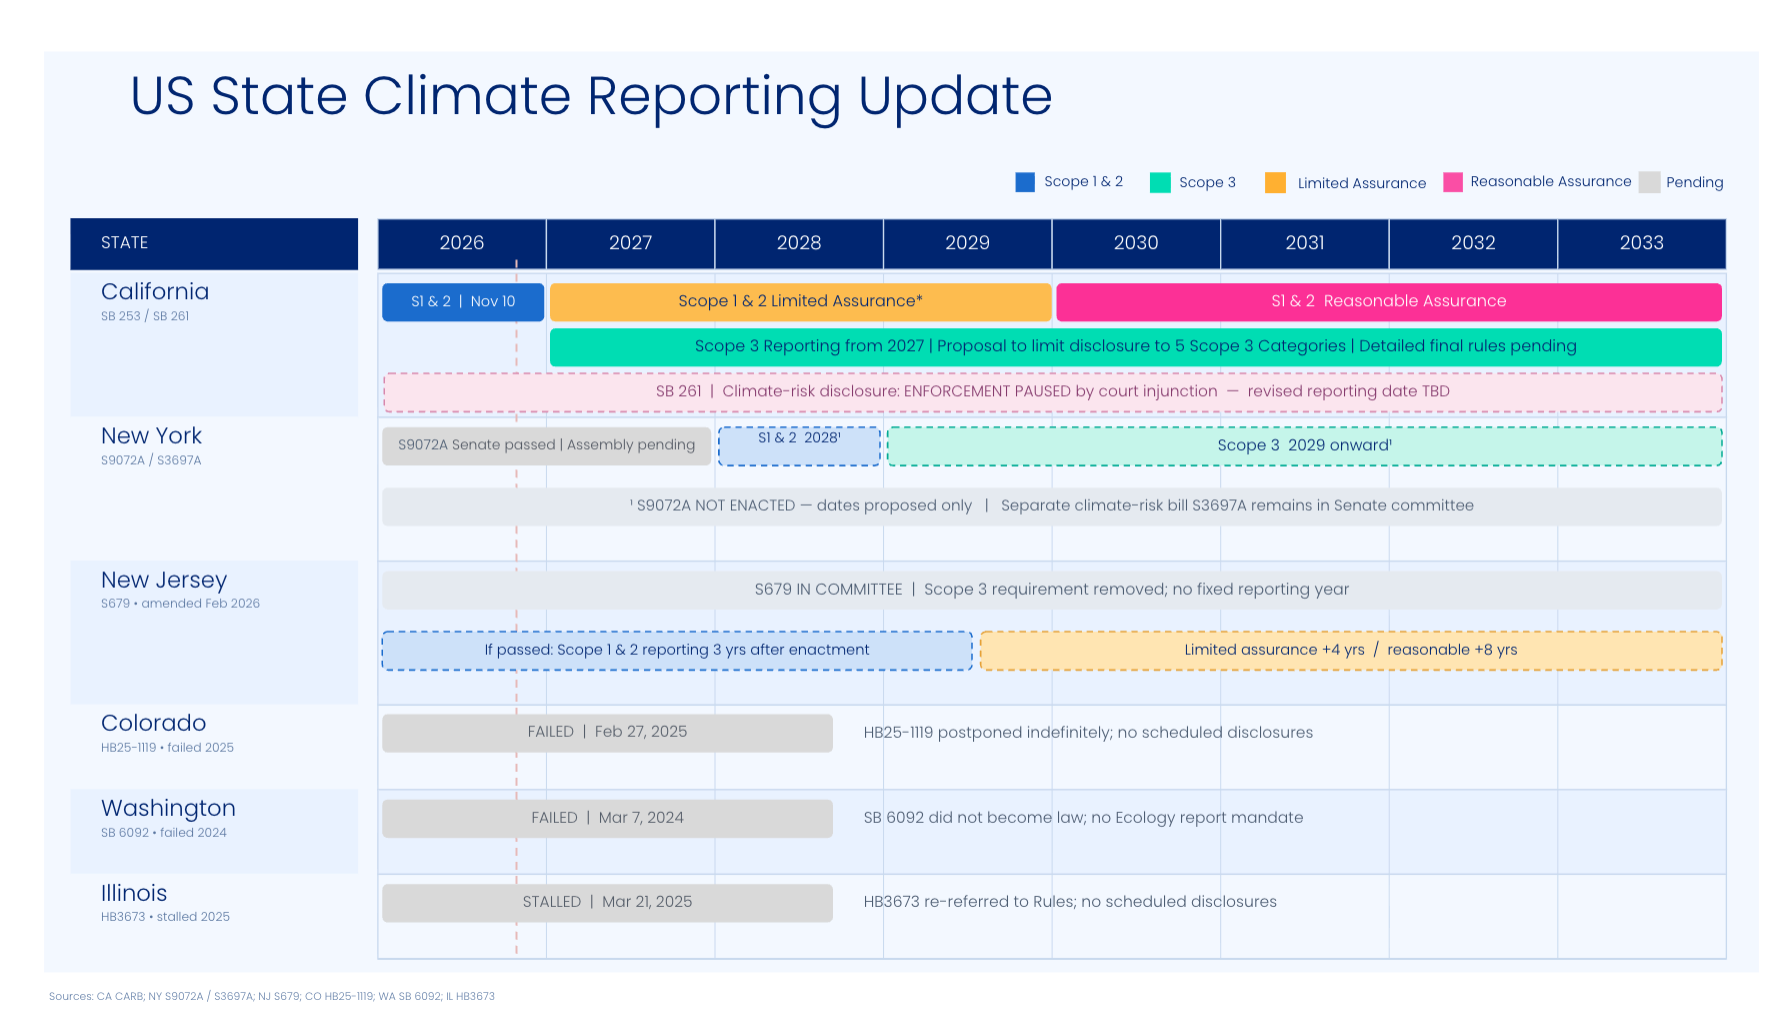
Several states have introduced bills modeled on SB 253, all using a $1 billion revenue threshold:
- New York: The Climate Corporate Data Accountability Act (S9072A) passed the State Senate 40-22 in February 2026, but the Assembly adjourned on June 5 without voting on it. The bill has been introduced in some form every year since 2022 and is expected to return in the 2027 session.
- New Jersey: S679 was reintroduced in 2026 and sits in the Senate Budget and Appropriations Committee. Its timeline runs from enactment, so public reporting would begin roughly four years after passage.
- Illinois: HB 3673 carried over into 2026 without further action.
- Colorado and Washington: Colorado's HB 25-1119 died in committee in 2025. Washington's SB 6092 was narrowed to a study directive and failed to pass the legislature.
None of these is law yet. The pattern still matters: every bill copies California's thresholds and largely accepts reports prepared for other jurisdictions, so a California-ready inventory is the foundation for whatever passes next. For a state-by-state breakdown, see our guide to U.S. state climate disclosure laws.
Pressure that does not depend on any regulator
Companies below every threshold are still being asked for climate data. SB 253 filers need Scope 3 numbers from 2027, which means their suppliers might be asked for emissions data whether or not any law applies to them directly. Customers, lenders, and investors are making the same requests through CDP, EcoVadis, and supplier sustainability questionnaires.
How to prepare now that state rules set the bar
1. Confirm which laws apply to you. "Doing business in California" is defined broadly, and revenue thresholds include subsidiaries. Many companies that assumed SEC filer status determined their obligations are in scope for SB 253 or SB 261 regardless.
2. Build a Scope 1 and 2 inventory that can survive assurance. Limited assurance starts in 2027. An auditor will ask for source data, emission factor selection, organizational boundaries, and documentation of every estimate. Inventories built in spreadsheets for internal use rarely hold up to that level of review without rework. Here's how spreadsheets, software, and expert support compare.
3. Start Scope 3 now. Scope 3 typically accounts for most of a company's footprint and can depend on data held outside of the company. Scope 3 surprises are one of the patterns we see across hundreds of corporate footprints.
4. Keep your climate risk assessment current. Even with SB 261 paused, a TCFD- or ISSB-aligned risk assessment supports SEC materiality judgments, investor questions, and an SB 261 report on short notice if the injunction is lifted.
5. Build one dataset, not one per regulator. California, a future New York or New Jersey law, CDP, and customer questionnaires all draw on the same underlying emissions and risk data. Structuring it once in a single platform, with audit-ready documentation, is far cheaper than rebuilding it for each request.
Talk to an expert
The end of the SEC rule did not simplify climate reporting. It moved requirements to the states and internationally, extended voluntary disclosure, expanded the SEC’s rule to private companies, and added Scope 3.
Good.Lab works with companies preparing for SB 253, SB 261, and any state laws that might follow. Our team combines GHG emissions software with hands-on consulting, so your inventory is assurance-ready from the start. Talk to an expert about your reporting obligations, a Scope 1, 2, and 3 inventory, or a climate risk assessment.
FAQs
Is the SEC climate rule still in effect?
No. The rule was adopted in March 2024 but stayed a month later and never took effect. The SEC proposed rescinding it entirely on May 29, 2026, and a final rescission vote is expected in late 2026 or early 2027.
Do public companies still have to disclose climate risks?
Yes, when they are material. Existing SEC disclosure requirements, explained in the Commission's 2010 climate guidance, still require material climate-related risks to appear in risk factors, management’s discussion and analysis, and other sections of SEC filings.
Does the SEC rescission affect California's climate laws?
No. SB 253 and SB 261 are state laws administered by the California Air Resources Board and apply independently of SEC rules, to both public and private companies.
When is the first SB 253 report due?
November 10, 2026, for Scope 1 and Scope 2 emissions. Scope 3 reporting and limited assurance on Scope 1 and 2 begin in 2027.
Is SB 261 enforceable?
Not currently. The Ninth Circuit enjoined enforcement on November 18, 2025, pending its decision in the Chamber of Commerce challenge. CARB will set a new deadline if the injunction is lifted.
Which other states have climate disclosure laws?
As of October 2026, only California has enacted mandatory corporate climate disclosure laws. New York, New Jersey, and Illinois have pending or recently introduced bills modeled on SB 253.