California’s first emissions disclosures, under SB 253, are expected on November 10th, 2026. The part of California’s climate disclosure law, SB 261, covering climate risk disclosures is currently under a court-ordered stay. Collectively, these bills are housed under SB 219.
Companies with more than $1 billion in total annual revenue that do business in California must report their Scope 1 and Scope 2 greenhouse gas emissions to the California Air Resources Board by November 10, 2026. Next November, they must report Scope 1, 2, and 3 emissions and get limited assurance on Scope 1 and 2.
The second half of the package, SB 261, is a different story. Its climate-related financial risk requirement was scheduled to take effect January 1, 2026. A Ninth Circuit injunction paused enforcement in November 2025, and no replacement date has been set.
SB 219 is the 2024 bill that amended both laws. You do not comply with SB 219. You comply with SB 253, SB 261, or both, depending on your revenue.
This guide covers who is covered, what's required in the first cycle, what CARB has said about 2027, and where the litigation stands.
Which Law Applies To You
Revenue under SB 219 is measured on total global revenue, not California revenue. This is the most common scoping mistake we see. A company headquartered in Ohio with $1.2 billion in global revenue and a sales office in Sacramento is in scope for both SB 253 and SB 261.
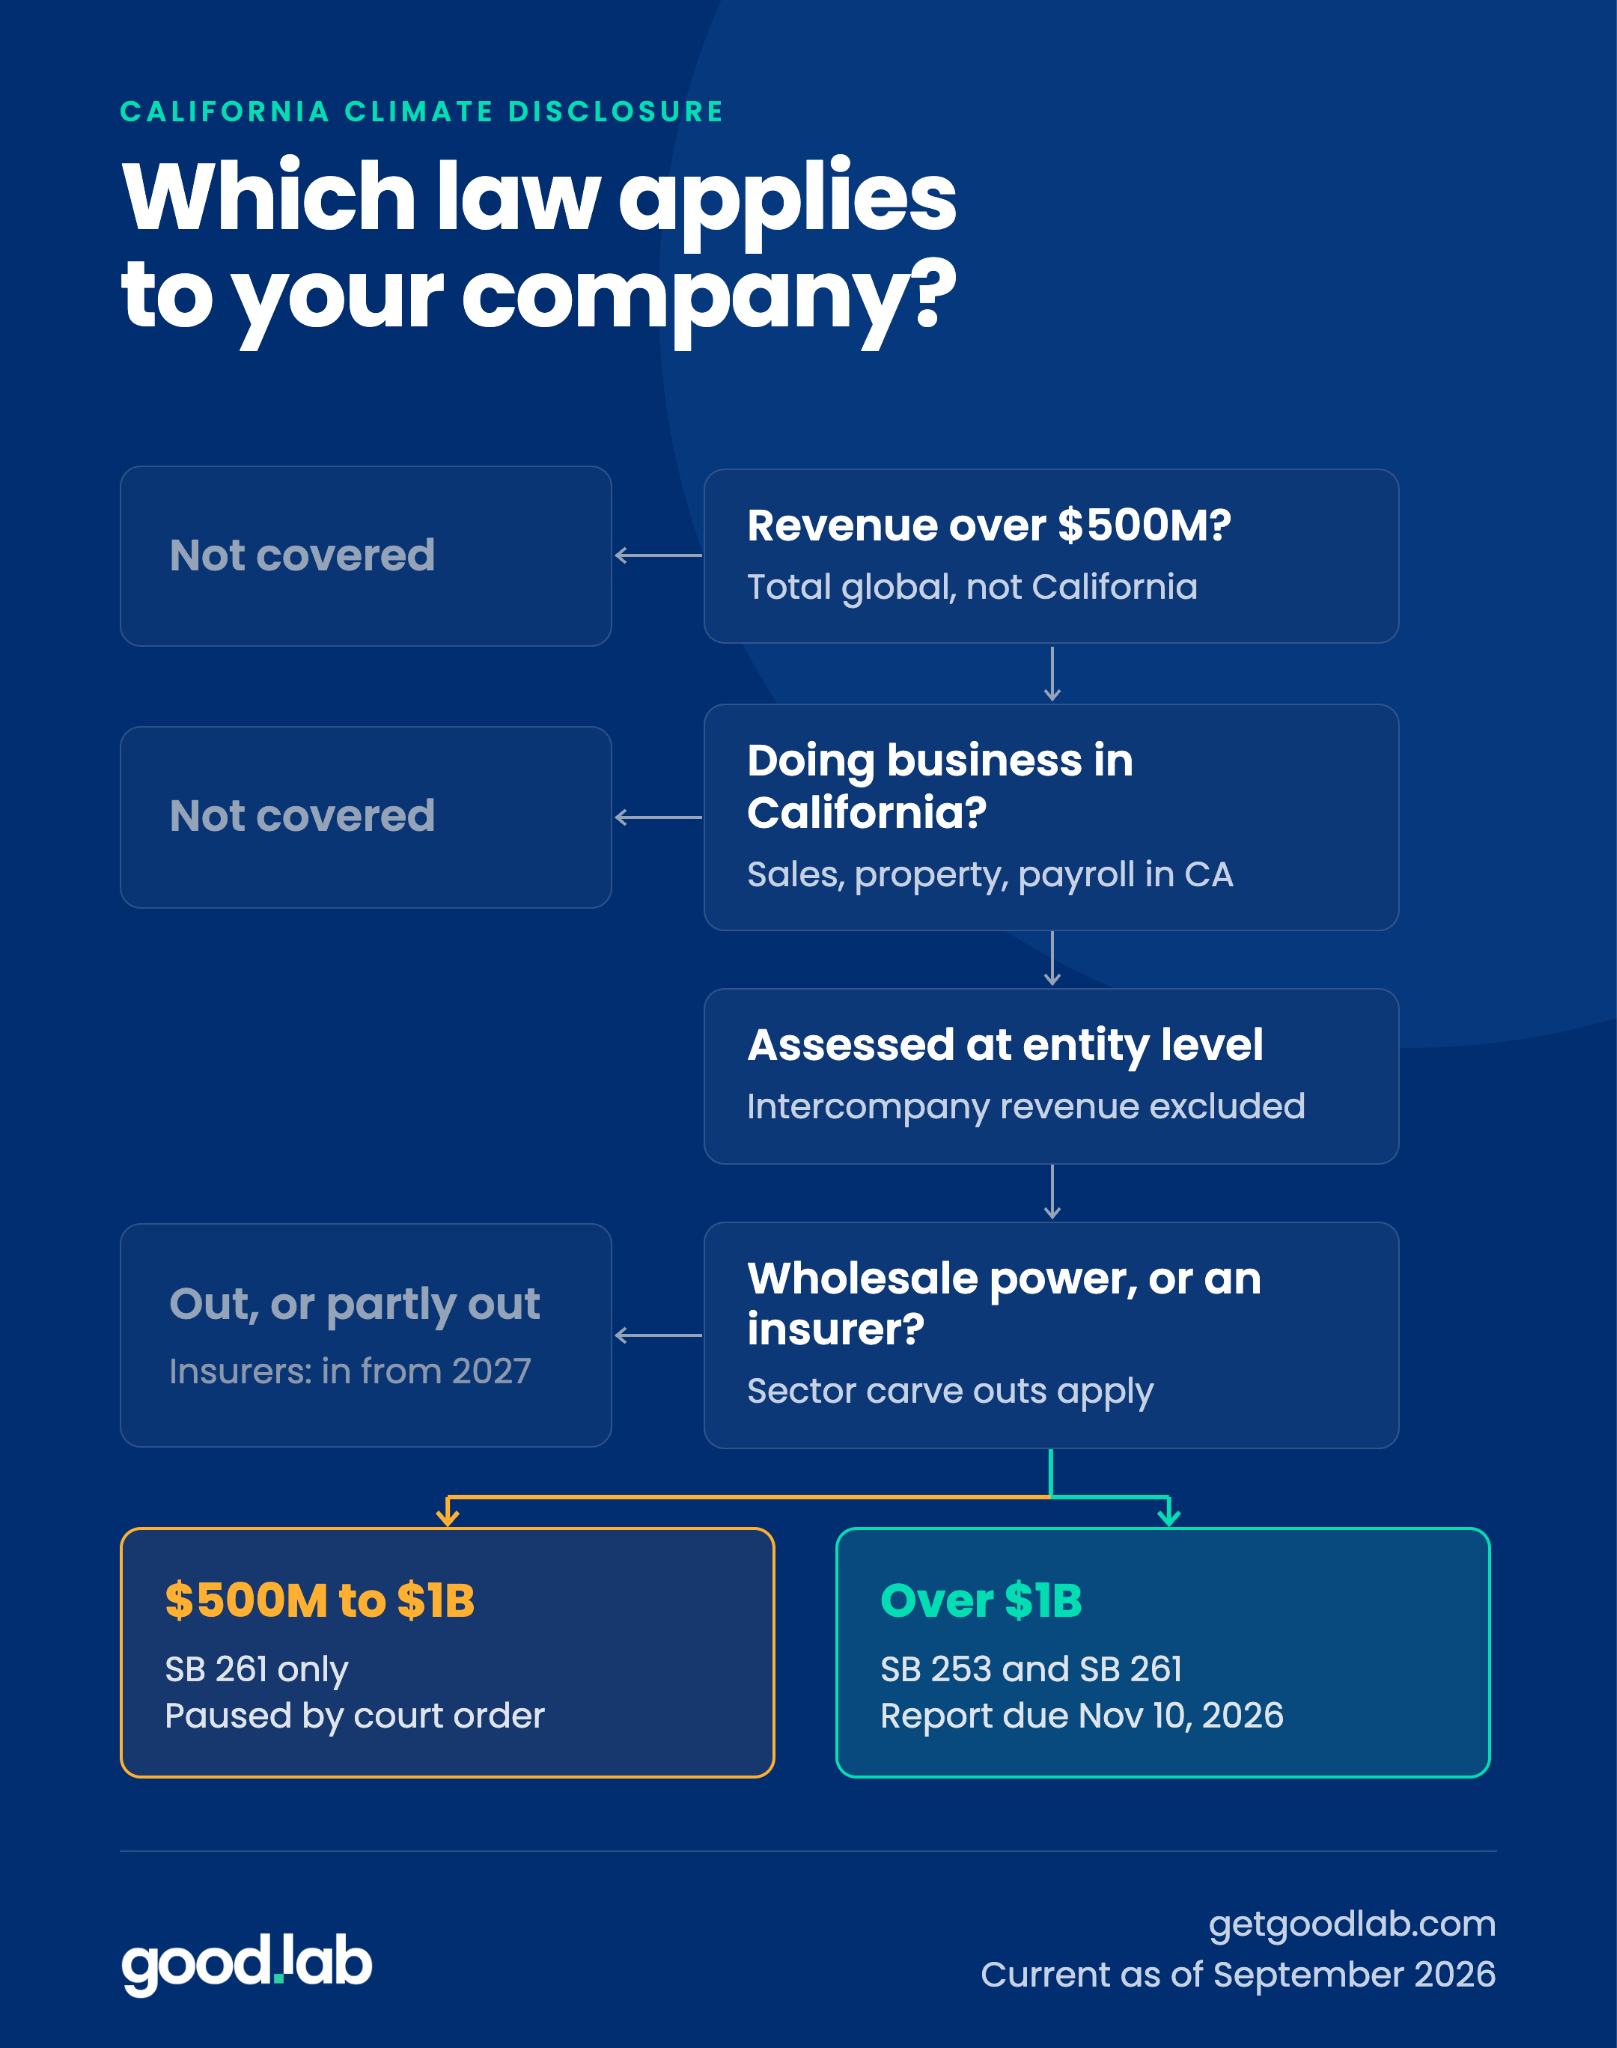
Regulated insurance companies are expressly exempt from SB 261 and were exempted from SB 253 for the 2026 reporting year. CARB has proposed bringing them under SB 253 starting in 2027.
"Doing business in California" is defined under Revenue and Taxation Code section 23101(b), which captures companies with California sales, property, or payroll above statutory thresholds, alongside those founded or domiciled in the state.
What is California SB 219
In September 2024, California enacted Senate Bill 219, which consolidates and amends SB 253 and SB 261. While the core requirements remain intact, changes included:
- CARB received expanded authority to define how the reporting rules work in practice, including the timing of Scope 3 disclosure.
- The requirement that reporting entities pay a filing fee at submission was removed, though a separate annual fee program remains.
- Scope 3 reporting was decoupled from the rigid 180-day window that followed Scope 1 and 2 submission under the original SB 253.
If you need to know what's required under SB 219, they are still covered by the SB 253 and SB 261 explained below.
SB 253: Greenhouse Gas Emissions Reporting
Who is covered
US companies with a total annual revenue exceeding $1 billion that do business in California.
CARB's recent SB 253 Final Guidance for 2026 reporting cleared up some edge cases around scoping:
- Applicability is assessed at the individual-entity level. Parent companies are not automatically swept in, because a subsidiary is a reporting entity.
- Wholesale electricity entities whose only California activity consists of wholesale electricity transactions occurring in interstate commerce are excluded entirely.
- Parent-level consolidation is permitted. You may consolidate both reports and fee payments at the parent level for a qualifying subsidiary that is itself a reporting entity.
If your company ran its applicability analysis in 2025, run it again. The definitions have changed slightly.
What is required in 2026
Scope 1 and Scope 2 emissions only. CARB also reiterated in its final guidance that it will provide enforcement discretion in year 1 and only expect Scope 1 and 2 reports from companies that started or planned to collect data at the time of the December 5th 2024 Enforcement Notice. However, companies that are not reporting still must provide a public-facing, company-headed letter explaining why they are not reporting.
- Scope 1: direct emissions from sources your company owns or controls, including facilities, fleet vehicles, and on-site combustion.
- Scope 2: indirect emissions from purchased electricity, steam, heat and cooling.
Both must be calculated in line with the Greenhouse Gas Protocol Corporate Accounting and Reporting Standard.
Which fiscal year of data does CARB expect
CARB has proposed tying the data year to your fiscal year, guaranteeing at least six months between fiscal year-end and the reporting deadline. In 2026, that would mean:
- Companies with fiscal years ending between January 1 and February 1: Report using data from the fiscal year ending in 2026.
- Companies with fiscal years ending between February 2 and December 31: Report using data from the fiscal year ending in 2025 (though companies can use 2026 data if it is already available).
CARB has indicated this approach could become permanent in 2027 and beyond and would extend to Scope 3.
How to submit
On September 1, 2026, CARB issued guidance for the first reporting cycle and opened a voluntary online Report Intake Platform. However, companies don’t have to use that in this first year. There are multiple options to simplify dislcosure:
- You can submit through the Report Intake Platform, or email your report and contact information to climatedisclosure@arb.ca.gov.
- CARB's draft Scope 1 and Scope 2 reporting template is also optional in year 1, but provides a good blueprint for the type of information CARB expects if you decide not to use it.
- CARB will accept an existing annual report that includes Scope 1 and Scope 2 figures, or emissions data already reported to another program or voluntary initiative, such as CDP.
👉 For a walkthrough of CARB's Scope 1 and 2 template, see our guide to reporting Scope 1 and 2 emissions under SB 253.
Assurance: not required for SB 253 this year, but is required next year
No third-party assurance is required for the 2026 reporting cycle.
That changes in 2027:
- 2027: limited assurance over Scope 1 and Scope 2 emissions from a qualified independent provider.
- 2030: reasonable assurance over Scope 1 and Scope 2 and limited assurance for Scope 3.
CARB has proposed recognizing several assurance standards: ISAE 3000 (Revised) and ISAE 3410 for engagements commencing before December 15, 2026; ISSA 5000 for engagements commencing on or after that date. However, CARB has acknowledged that this approach is not final and will provide more guidance in 2027.
One thing to note for 2026 is that your inventory needs to be built this year to survive limited assurance in 2027. Companies that will struggle with assurance next year are those whose 2026 submission lacked a documented methodology.
The annual fee
Every reporting entity and covered entity pays an annual fee (estimated at $3,106 in 2026). Under CARB's Final Guidance for 2026:
- CARB will issue a written fee-determination notice by December 10, 2026.
- Payment is due within 60 calendar days of the notice date.
- Fee payments may be consolidated at the parent-company level for qualifying subsidiaries.
Penalties and first-year enforcement
Penalties under SB 253 reach up to $500,000 per reporting year. Two safe harbors have been proposed to apply to Scope 3 from 2027:
- No penalties for inaccuracies in Scope 3 reporting where the disclosure was made on a reasonable basis and in good faith.
- Between 2027 and 2030, Scope 3 penalties apply only to non-submission, not to errors.
The more important point for 2026 is CARB's enforcement posture. Consistent with its December 5, 2024 Enforcement Notice, CARB has signaled a good-faith, best-available-data approach to the first Scope 1 and Scope 2 reports. While this is not a pass to do nothing this year, it means that as long as you provided evidence that you were not planning to collect data when the Enforcement Notice was released, document your data sources, your assumptions, the gaps you could not close, and your plan to close them, that is considered good-faith reporting.
SB 261: Climate-Related Financial Risk Reporting
Who is covered
US-based companies with total annual revenue exceeding $500 million that do business in California. Regulated insurance companies are expressly exempt.
What is required
A climate-related financial risk report, published every two years, covering both physical and transition risks and the measures the company is taking to mitigate and adapt to them.
Reports must follow the Task Force on Climate-related Financial Disclosures (TCFD) framework, organized around the TCFD’s four pillars of reporting: governance, strategy, risk management, and metrics and targets. The International Sustainability Standards Board’s (ISSB) IFRS S2 is also accepted. Companies already reporting under TCFD or ISSB standards can use that work to satisfy SB 261.
The statute operates on a report-or-explain basis. Companies unable to disclose fully must publish what they have, explain the gaps, and describe how they intend to close them.
Covered entities must publish the report on their own website and submit it to CARB's public docket.
Where SB 261 actually stands
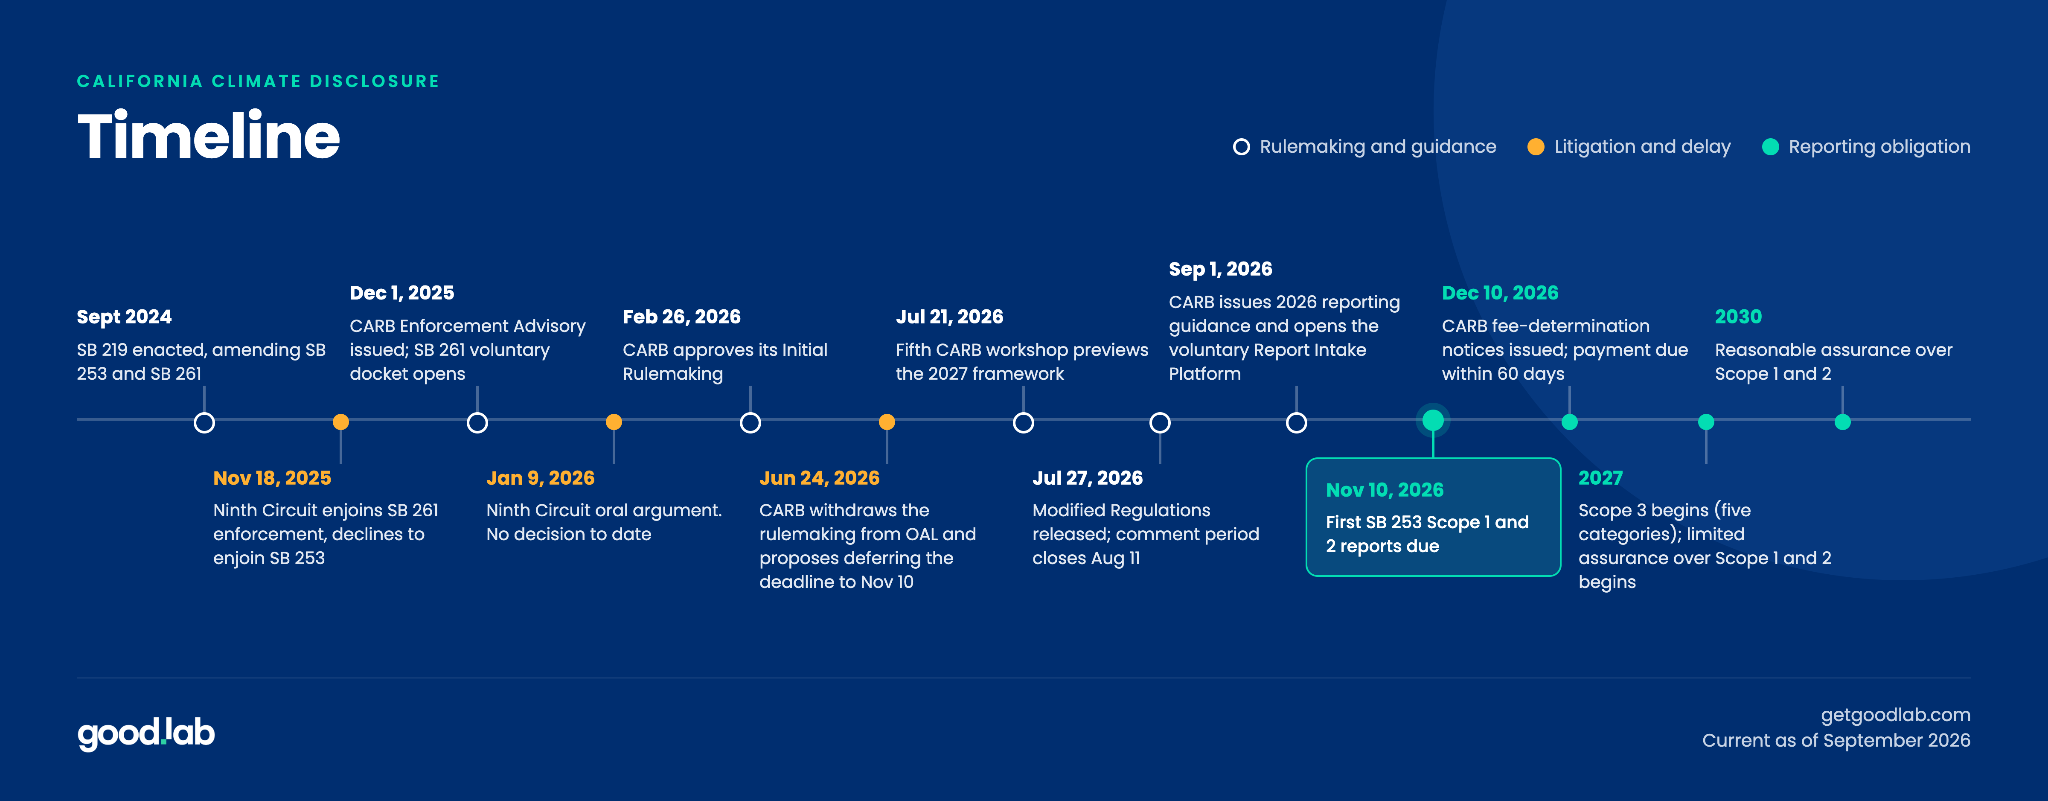
On November 18, 2025, the Ninth Circuit granted an injunction pending appeal halting enforcement of SB 261. The same order declined to enjoin SB 253, which is why one law is live, and the other is not.
On December 1, 2025, CARB issued an Enforcement Advisory confirming it would not take action against entities that missed the January 1, 2026 statutory deadline, and opened a public docket for companies choosing to file voluntarily. CARB has said it will announce an alternate reporting date once the appeal resolves.
The Ninth Circuit heard oral argument on January 9, 2026, in Chamber of Commerce v. Randolph. The panel focused on whether SB 261's narrative disclosure requirement compels speech on contested policy questions, and on the burden of SB 253's Scope 3 requirement. No decision has been issued as of September 2026.
A separate challenge, Exxon Mobil Corp. v. Sanchez, was filed in the Eastern District of California in October 2025 and adds a claim that SB 261 is preempted by the National Securities Markets Improvement Act. That case is effectively on hold pending the Ninth Circuit's decision.
What this means practically
The injunction pauses SB 261. However, CARB still opened up its climate risk reporting docket. So far, around 200 companies (less than 5% of the number expected to be impacted) have reported. Companies can report ahead of time, and if the Ninth Circuit allows the rule to proceed, obligations can resume quickly, with no guarantee of a generous runway.
The reasonable posture is readiness to ensure you already have a TCFD- or ISSB-aligned report, so you can quickly submit when the new deadline is made.
SB 219 Timeline
What to do between now and November 10
By now you should have your Scope 1 and 2 inventory ready if you are reporting and have built a good-faith record of data sources, methodology, emission factors, exclusions, and the reasoning behind them. This is what CARB's first-year enforcement posture is designed to reward, and what an assurance provider will ask for in 2027.
The only thing left is to decide how you will report via the Intake Platform, email, CARB's template, or an existing report, and plan to pay the fee during the 60-day payment cycle after December 10th.
What is coming for SB 253 in 2027
CARB previewed the next phase at its July 2026 workshop. None of it is adopted, and a draft of the subsequent rulemaking is expected later in early 2027, followed by another 45-day comment period. But the direction is now visible, and it is more manageable than most companies expect.
Scope 3 is likely to start narrow. CARB has proposed limiting mandatory Scope 3 reporting in the 2027 cycle to five of the fifteen most used GHG Protocol Scope 3 Categories:
- Category 1: Purchased Goods and Services
- Category 3: Fuel- and Energy-Related Activities
- Category 5: Waste Generated in Operations
- Category 6: Business Travel
- Category 7: Employee Commuting
The remaining ten categories stay voluntary, but could become mandatory at a later date.
Insurance companies come into scope. CARB indicated that Department of Insurance reporting, which excludes Scope 3 and assurance, may not satisfy SB 253. From 2027, insurers would either file a single report satisfying both regimes or supplement their CDI filing.
How California fits the wider picture
CARB has used widely adopted standards like the GHG Protocol, TCFD, and ISSB to maximize interoperability with other regulations, like the more than 40 jurisdictions that use the ISSB standards the EU's Corporate Sustainability Reporting Directive (CSRD), and voluntary frameworks like CDP.
The practical upshot is that companies already reporting under CSRD, ISSB, and CDP can leverage existing reports to comply more easily. In the first year, alignment is largely automatic. In subsequent years, you may need to adapt slightly, but the underlying data will be there.
Several US states have also introduced climate disclosure legislation modeled on California's approach.
👉 We track the current status of each of those in our multi-state climate reporting regulatory tracker.
How Good.Lab Can Help
Most companies facing their first California filing should already have their year one Scope 1 and 2 ready, but 2027 is coming up quickly, and it's where the rubber really hits the road. To ensure companies are ready for compliance when Scope 3, full enforcement, and assurance kick in, we work with companies to:
- Building a defensible, expert-guided, software-supported Scope 1, 2, and 3 inventory aligned to the GHG Protocol and structured to hold up under assurance
- Preparing your submission, whether through CARB's template, the intake platform, or an existing report, we will ensure you are ready to submit through whatever process CARB prefers in 2027.
- Assessing climate-related financial risk for SB 261, so you're prepared the moment deadlines are reinstated
Questions? Book an initial call with us here and we'll walk through it together.
FAQs
What is the SB 253 reporting deadline? Scope 1 and Scope 2 emissions reports are due November 10, 2026, deferred from an earlier proposed date of August 10, 2026.
Do I need third-party assurance for my 2026 report? No. CARB has confirmed that no assurance is required for the 2026 cycle and that it will accept submissions with or without it. Limited assurance over Scope 1 and Scope 2 begins in 2027 and escalates to reasonable assurance by 2030.
Do I have to report Scope 3 emissions this year? No. Scope 3 is not required for the 2026 reporting year. CARB has proposed that mandatory Scope 3 reporting begin in 2027, limited to five of the fifteen GHG Protocol categories.
Is SB 261 still in effect? The statute is in effect, but enforcement is paused. A Ninth Circuit injunction issued in November 2025 blocked CARB from enforcing the January 1, 2026 deadline. CARB has said it will set an alternate date once the appeal resolves. Voluntary filing through CARB's public docket remains available.
What did SB 219 change? SB 219 amended SB 253 and SB 261 in September 2024. It gave CARB expanded authority over how the rules are implemented and decoupled Scope 3 reporting from the original 180-day window. The core obligations were unchanged.
Is revenue measured on California sales or total revenue? Total annual revenue, measured globally. A company can be well below the threshold on California sales and still be covered.