
The International Sustainability Standards Board (ISSB) issued its first two standards, IFRS S1 and IFRS S2, in June 2023. Three years later, the question is no longer whether they meet their goal of becoming the global baseline for sustainability disclosure. It is how quickly that baseline reaches your company and how you should prepare.
According to the IFRS Foundation, more than 45 jurisdictions have now adopted the ISSB Standards or are taking steps to introduce them. The United States is not one of them. That does not mean US companies are outside of their reach. ISSB requirements arrive through foreign listings and subsidiaries, through the CDP questionnaire, through California's climate risk law, and through the Scope 3 data requests large customers impacted by ISSB-aligned rules send to their suppliers.
This guide covers what the standards require, what has changed since they were created in 2023 (including the ISSB's new nature-related disclosure proposal), where reporting is mandatory, and how to prepare.
What are the ISSB standards?
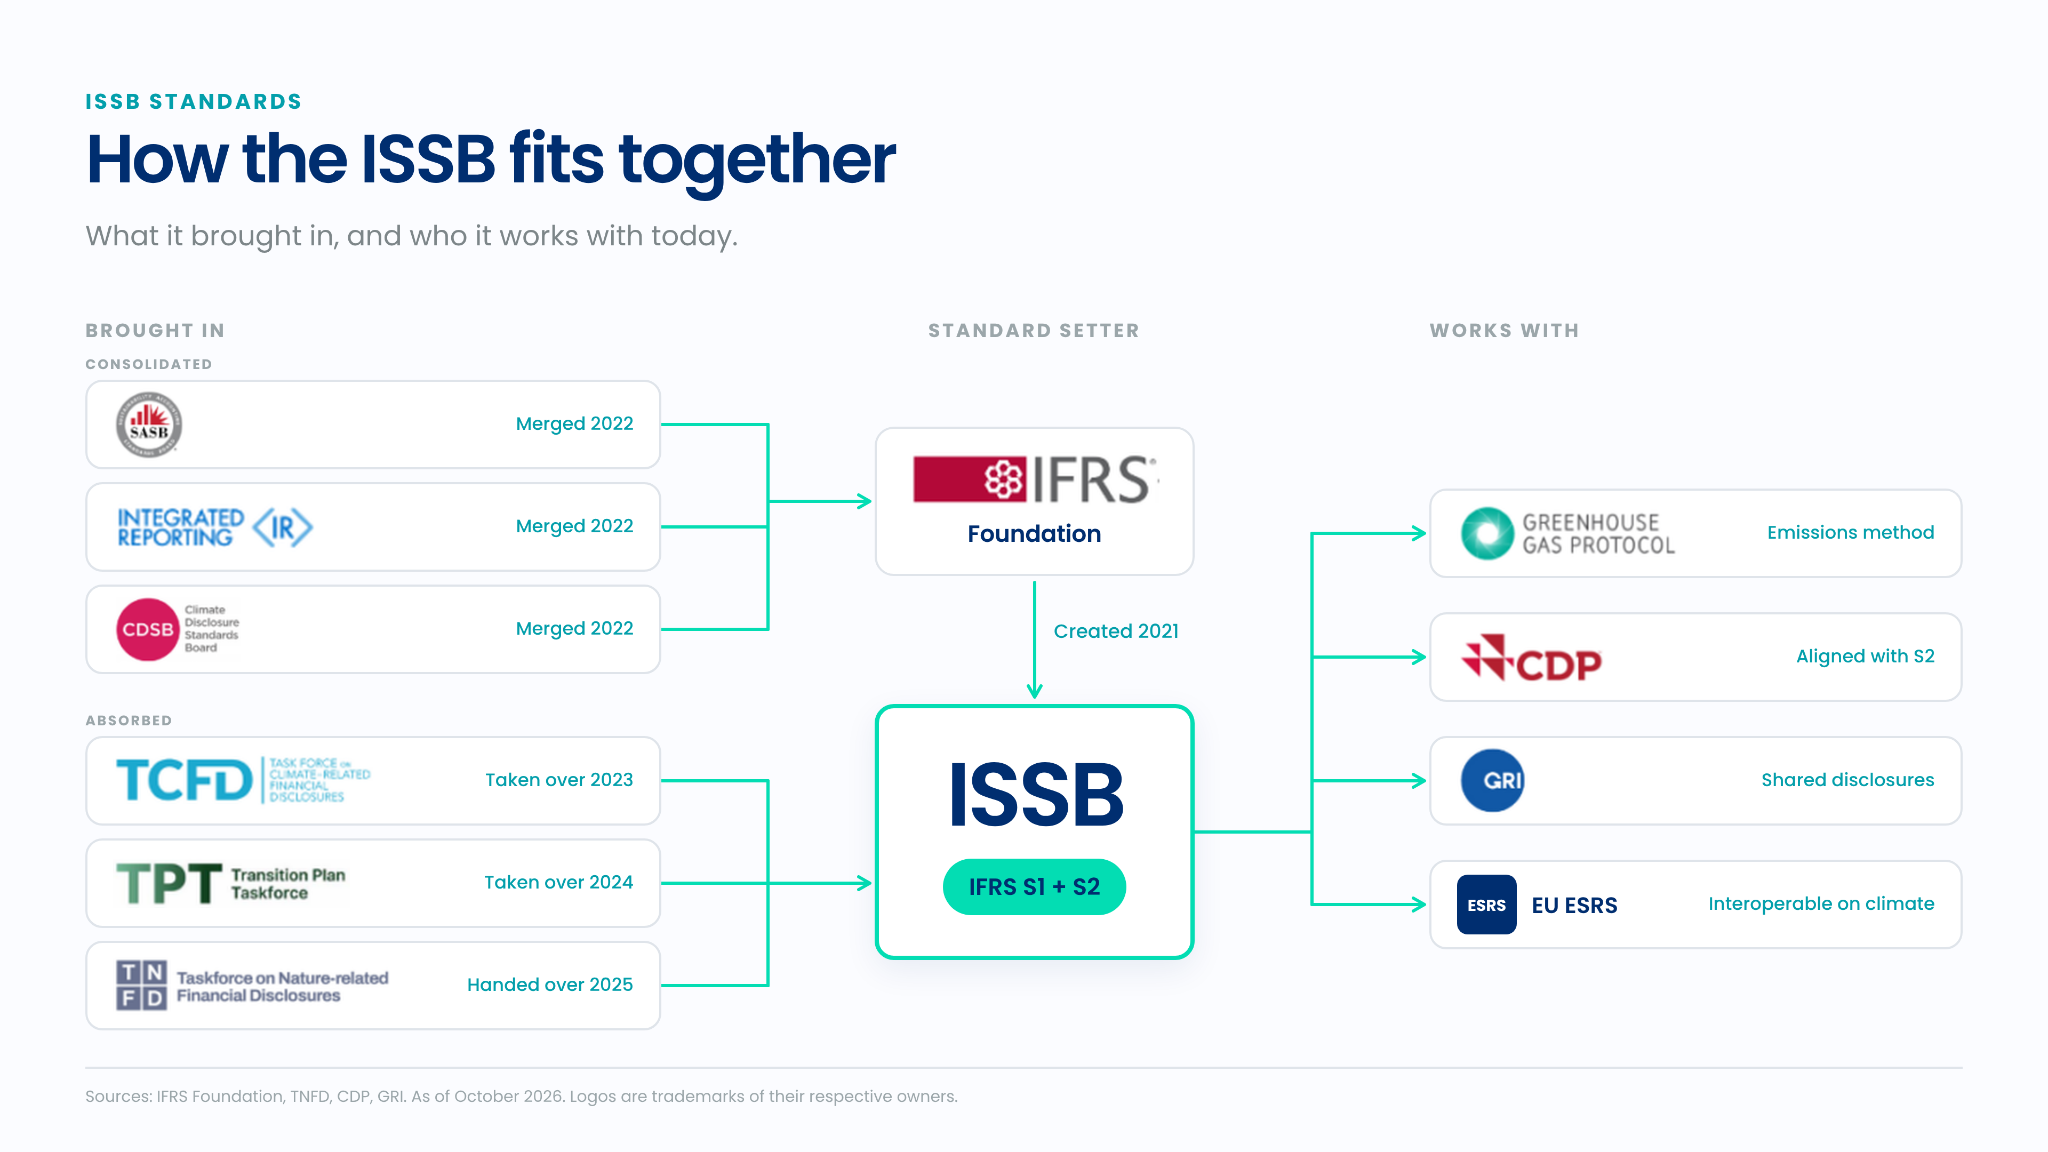
The IFRS Foundation launched the ISSB in November 2021 at COP26 in Glasgow to create a single global baseline for investor-focused sustainability reporting. It absorbed the Climate Disclosure Standards Board (CDSB) and the Value Reporting Foundation, which housed the SASB Standards and the Integrated Reporting Framework. When the Task Force on Climate-related Financial Disclosures (TCFD) disbanded in October 2023, the ISSB took over monitoring of company climate disclosures.
The ISSB published two standards on June 26, 2023:
- IFRS S1, General Requirements for Disclosure of Sustainability-related Financial Information
- IFRS S2, Climate-related Disclosures
The International Organization of Securities Commissions (IOSCO) endorsed the standards in July 2023 and called on its members to consider them in their sustainability disclosure regulatory frameworks.
The ISSB Standards use investor-focused materiality, where Information is material if omitting, misstating, or obscuring it could reasonably be expected to influence investors' and lenders' decisions.
IFRS S1 vs. IFRS S2
The two standards work together. S1 sets the general rules for sustainability disclosure. S2 applies those rules to climate.
Both standards use the four reporting pillars developed by the TCFD:
- Governance: how the board and management oversee sustainability and climate-related risks and opportunities.
- Strategy: how those risks and opportunities affect the business model, strategy and financial position, now and over the short, medium and long term.
- Risk management: how the company identifies, assesses, prioritizes and monitors them, and how that process fits into overall risk management.
- Metrics and targets: how the company measures performance, including progress against any targets it has set or is required to meet.
Transition reliefs in the first year
The ISSB built in reliefs for a company's first year of reporting:
- Report on climate only (IFRS S2), and add other sustainability topics under IFRS S1 in year two
- Omit Scope 3 GHG emissions in the first year
- Skip comparative information in the first year
- Continue using a measurement method other than the GHG Protocol if one was already in use before first application
What has changed since 2023
Targeted amendments to IFRS S2
On December 11, 2025, the ISSB issued targeted amendments to the greenhouse gas requirements in IFRS S2. They take effect for annual periods beginning on or after January 1, 2027, with early application permitted. The amendments:
- Allow banks, asset managers and insurers to limit Scope 3 Category 15 (investments) emissions to financed emissions, with a required financed emissions subtotal, allowing them to leave out facilitated emissions
- Clarify that a company can use a non-GHG Protocol measurement method for the part of the business where a regulator requires it
- Add similar relief for global warming potential (GWP) values required by local regulators
Most of the changes matter to financial institutions. For everyone else, the core Scope 3 requirement is unchanged.
New topics and closer coordination
- Nature. In October 2026, the ISSB proposed its first nature-related disclosure requirements as a Practice Statement, not a new standard. The section below covers what it proposes.
- SASB Standards. The ISSB is updating the industry-based SASB Standards that underpin S1 and S2 metrics.
- GRI. In May 2026, the ISSB and the Global Reporting Initiative (GRI) expanded their collaboration to identify common disclosures and coordinate on nature, sector standards and human capital.
- EU interoperability. The European Commission adopted the revised ESRS on July 3, 2026, bringing them closer to the ISSB Standards. Companies can now use SASB-based industry guidance to meet ESRS entity-specific disclosure requirements and present information in formats that build from an ISSB report.
ISSB nature-related disclosures: the 2026 exposure draft
On October 22, 2026, timed to the UN biodiversity conference (COP17), the ISSB published an exposure draft of IFRS Sustainability Disclosure Practice Statement 1, Nature-related Disclosures. It is the ISSB's first step beyond climate into a specific environmental topic. Comments are open until February 19, 2027.
A Practice Statement, not a new standard
In April 2026, the ISSB decided against a standalone nature standard. The proposed Practice Statement is applied alongside IFRS S1 and S2 instead. The reasoning is that IFRS S1 already requires companies to disclose material nature-related risks and opportunities. The Practice Statement adds detail on how to do it well.
That has three practical consequences:
- It does not change any requirement in IFRS S1 or S2.
- A company can state compliance with the ISSB Standards without applying the Practice Statement. A company that does apply it and meets every requirement states compliance with the Practice Statement separately.
- Jurisdictions can decide whether to require it.
The consultation also asks whether a Practice Statement is the right form. After reviewing feedback, the ISSB could still issue the content as a standard.
Where ISSB reporting is required
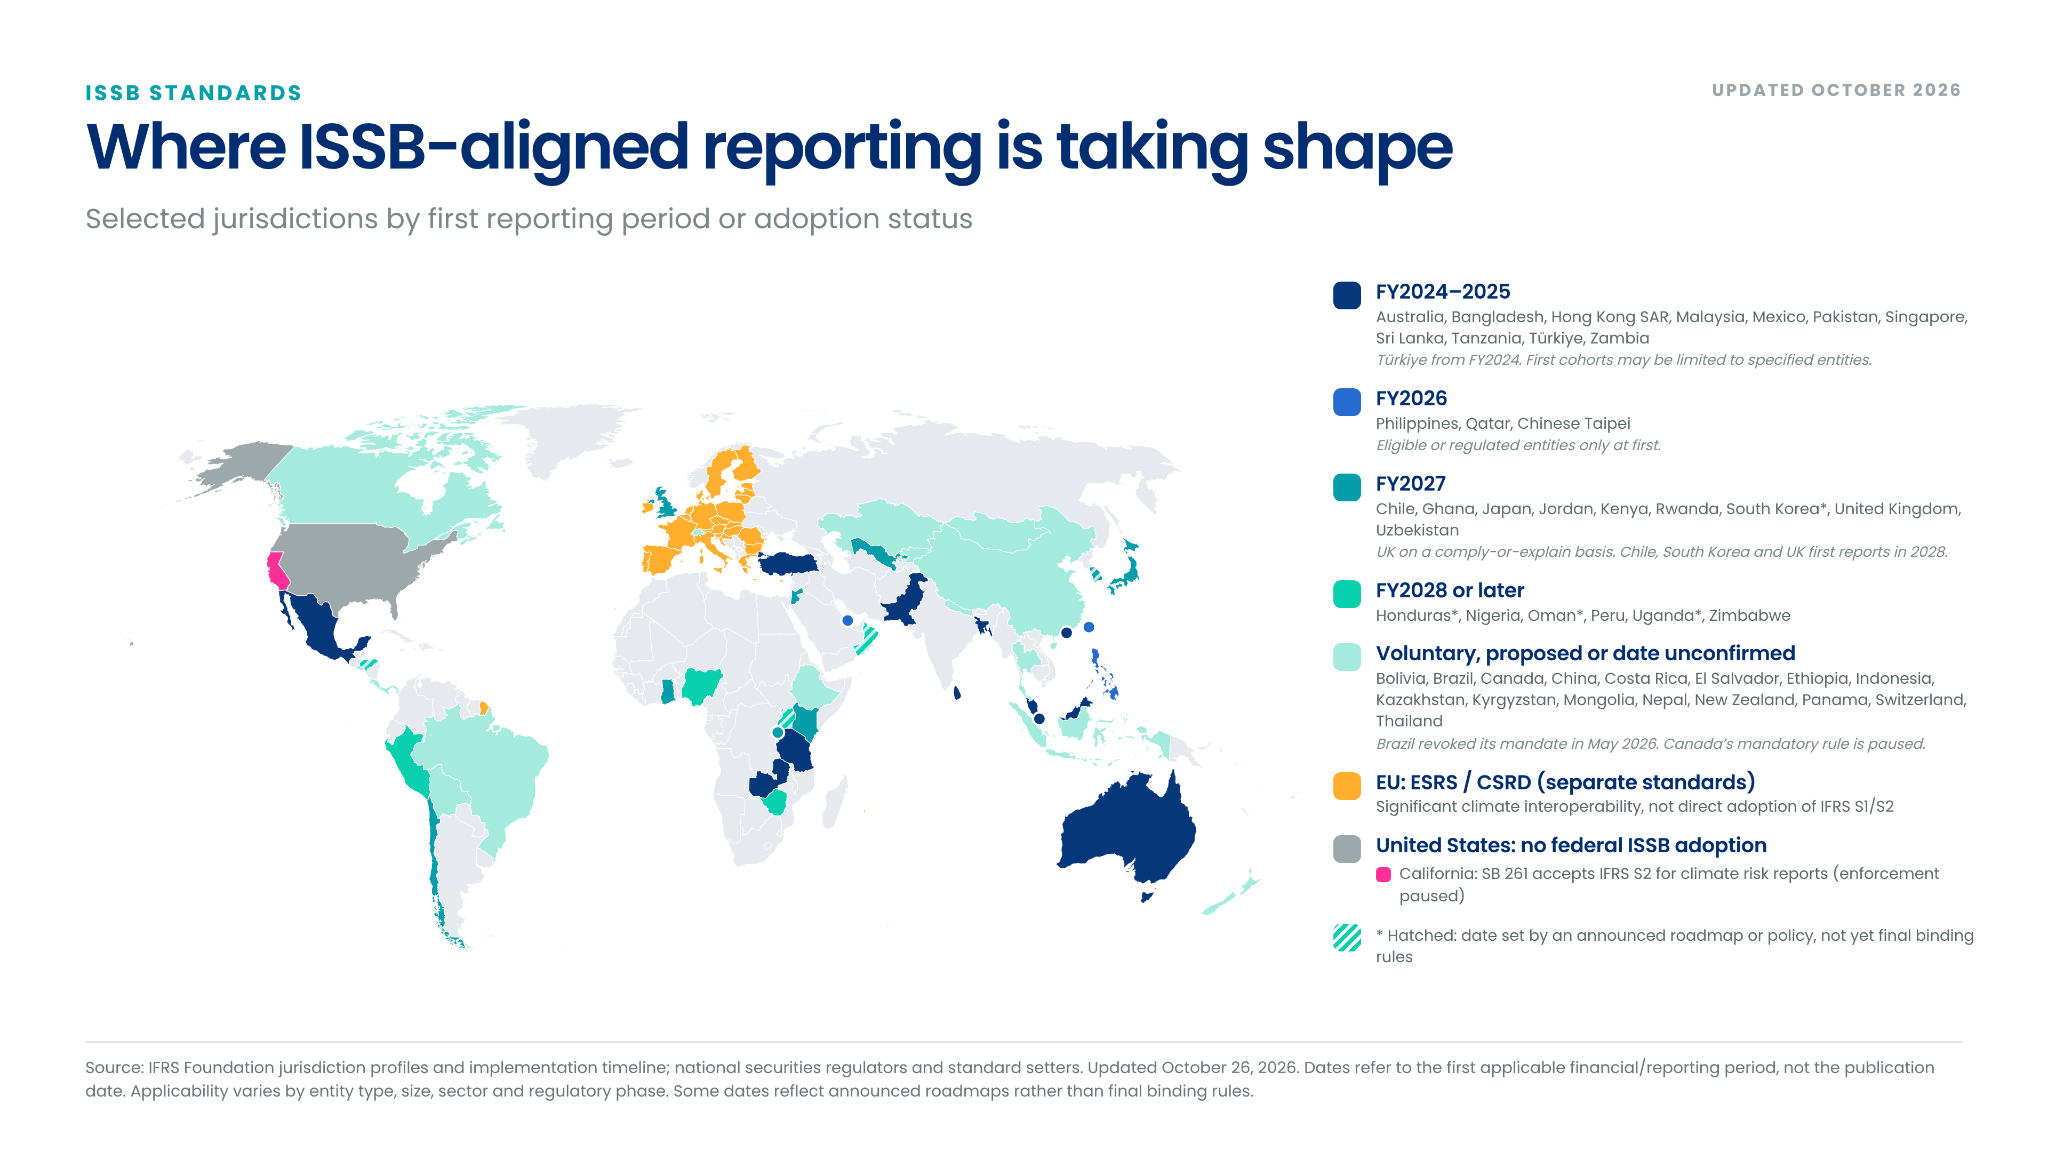
As of September 2026, the IFRS Foundation has published finalized profiles for 22 jurisdictions and snapshots for 14 more whose approaches are still being finalized.
Approaches vary widely: some adopt IFRS S1 and S2 word for word, some adopt only the climate requirements, and some issue local standards based on the ISSB baseline. Adoption timelines vary widely, but most plan to adopt before 2030.
How the ISSB standards reach US companies
The US has no federal ISSB mandate, and the SEC's climate rule never took effect. US companies still meet ISSB requirements in four ways.
1. Global operations and listings. Companies listed in, or with large subsidiaries in, Australia, Japan, the UK, Singapore, or Hong Kong fall under local ISSB-based rules. Several jurisdictions, including Japan and Hong Kong, already let companies satisfy local requirements by reporting under the ISSB Standards as issued.
2. CDP. Since 2024, the CDP corporate questionnaire has used IFRS S2 as its baseline for climate disclosure. In CDP's analysis of 2025 responses, 87% of companies disclosed against at least 80% of the IFRS S2-aligned questions. If your customers ask you to respond to CDP, you are already answering ISSB-aligned questions.
3. California. SB 261 requires companies with more than $500 million in revenue that do business in California to publish biennial climate-related financial risk reports, and IFRS S2 is one of the accepted frameworks. Enforcement is currently paused by a Ninth Circuit injunction issued November 18, 2025, but companies are filing voluntarily on CARB's public docket. Its companion law, SB 253, is not paused, and first Scope 1 and 2 emissions reports are due November 10, 2026. See our California SB 253 and SB 261 compliance support and our guide to state climate disclosure laws for more.
4. Customer Scope 3 requests. A company reporting under IFRS S2 must disclose its Scope 3 emissions in year 2 of reporting, and that figure includes its suppliers' emissions. That data request flows down the value chain whether or not the supplier is regulated itself, usually as a supplier sustainability questionnaire.
How to prepare for ISSB reporting
Most companies underestimate the gap between the climate disclosures they already make and what IFRS S2 requires. These five steps are where we start with clients, and where first-time reporters most often go wrong.
1. Confirm whether and when the standards apply
Map every route by which ISSB requirements reach you: jurisdictions where you are listed or have significant operations, CDP requests, California obligations, and customer requirements. The answer sets your deadline, your scope, and which transition reliefs you can use. Companies that skip this step often discover a requirement when a customer or regulator raises it.
2. Run a financial materiality assessment
IFRS S1 requires disclosure of every sustainability-related risk and opportunity that could reasonably be expected to affect your company's financial prospects. A structured materiality assessment defines what you have to disclose and gives you a defensible record of why.
3. Build an assurance-ready GHG inventory
IFRS S2 requires Scope 1, 2, and 3 emissions measured under the GHG Protocol, and most mandatory regimes add limited assurance within one to two years. An inventory assembled in spreadsheets for a voluntary report rarely withstands an assurance provider's review. Start with Scope 1 and 2, then work through the material Scope 3 categories, documenting methods, emission factors, and data sources as you go. Our GHG emissions inventory work is built for that standard, and we have written about the patterns we see across hundreds of corporate carbon footprints to ensure you don’t make any common mistakes we see.
4. Close the gaps against your existing disclosures
If you already report to CDP or follow TCFD, much of your governance and risk management content carries over. The gaps usually fall in three areas: climate scenario analysis, the current and anticipated financial effects of climate risks, and transition plan details. These areas require judgment, and regulators and assurance providers look most closely at them.
5. Assign data ownership across functions
ISSB disclosures sit next to the financial statements, so finance, legal, operations, and procurement all hold part of the data. Set clear ownership, controls and timelines early. The ISSB's connected reporting requirement means sustainability figures need the same discipline as financial ones.
What to look for in ISSB reporting software
Software makes ISSB reporting repeatable, but only if it is built for assurance and for more than one framework. When you evaluate ISSB reporting software, check for:
- GHG Protocol-based Scope 1, 2 and 3 calculations, with every emission factor and data source documented
- An audit trail that shows how each figure was produced, so an assurance provider can follow it
- Framework mapping, so one dataset feeds IFRS S2, CDP, ESRS and California's SB 253 and SB 261 without being rebuilt for each
- Supplier data collection capabilities for Scope 3, where most of the effort for climate disclosure is sits
- Support for the qualitative disclosures: governance, risk management, scenario analysis and financial effects
That last point is where software alone falls short. Choosing scenarios, judging materiality, and estimating financial effects are methodology decisions, and regulators and assurance providers question them most.
We compared the options in carbon accounting software vs. DIY vs. expert guidance, and it is why the Good.Lab platform comes with consultants who do that work alongside you.
Get ISSB-ready with Good.Lab
The ISSB Standards are now the reference point for climate and sustainability disclosure worldwide. The data the ISSB standards require reaches US companies through regulators, investors, and customers alike.
Good.Lab pairs a GHG accounting and sustainability reporting platform with experienced sustainability consultants, so your inventory, materiality assessment, and disclosures are built to hold up under assurance from the first year. Talk to an expert about where the ISSB Standards apply to your business and what to do first.
FAQs
What is the difference between IFRS S1 and IFRS S2?
IFRS S1 sets general requirements for disclosing all material sustainability-related risks and opportunities. IFRS S2 applies those requirements to climate, adding specific disclosures such as Scope 1, 2 and 3 GHG emissions, scenario analysis and transition plans.
Are the ISSB standards mandatory?
Only where a jurisdiction adopts them. More than 45 jurisdictions have adopted the ISSB Standards or are taking steps to do so, with mandatory reporting already in effect in markets including Australia, Singapore and Malaysia, and coming in Japan from 2027.
Has the United States adopted the ISSB standards?
No. There is no federal requirement, and the SEC has proposed rescinding its own climate disclosure rule, which was based on the ISSB standards. US companies still face ISSB requirements through CDP, international regulations, customer data requests, and state-level disclosure mandates, such as California's SB 261.
Do the ISSB standards require Scope 3 emissions?
Yes. IFRS S2 requires Scope 1, 2, and 3 GHG emissions, with relief from Scope 3 in the first reporting year. Several jurisdictions have extended or narrowed that requirement, so check local rules.
How do the ISSB standards relate to CDP and TCFD?
The ISSB Standards build on the TCFD's four pillars, and the ISSB took over the TCFD's responsibilities after the TCFD disbanded in 2023. CDP has aligned its questionnaire with IFRS S2 since 2024.
Is the ISSB creating a nature standard?
Not at this stage. On October 22, 2026, the ISSB published an exposure draft of a Practice Statement on nature-related disclosures, to be applied alongside IFRS S1 and S2. Comments close February 19, 2027, and the ISSB could still decide to issue the content as a standard.
Do I need software for ISSB reporting?
Not strictly, but spreadsheets rarely hold up once assurance is required. Software helps with emissions calculations, data collection, and audit trails. Judgment-heavy disclosures, such as scenario analysis and financial effects, still require experienced people.